How to submit a claim and negotiate a roof replacement with your insurance company
By Kristy Snyder•Last updated May 3, 2023
Last updated May 3, 2023
Table of Contents
- Understand exactly what your homeowners insurance policy covers
- Find out if there’s a limit on the roof’s age
- Gather proof that you’ve maintained your roof
- Inspect the roof to see what’s damaged
- Call roofing contractors for an estimate
- File a claim ASAP
- Mistakes to avoid when filing a claim
- Hire a roofing contractor near you
Find local pros for your project
Search for pros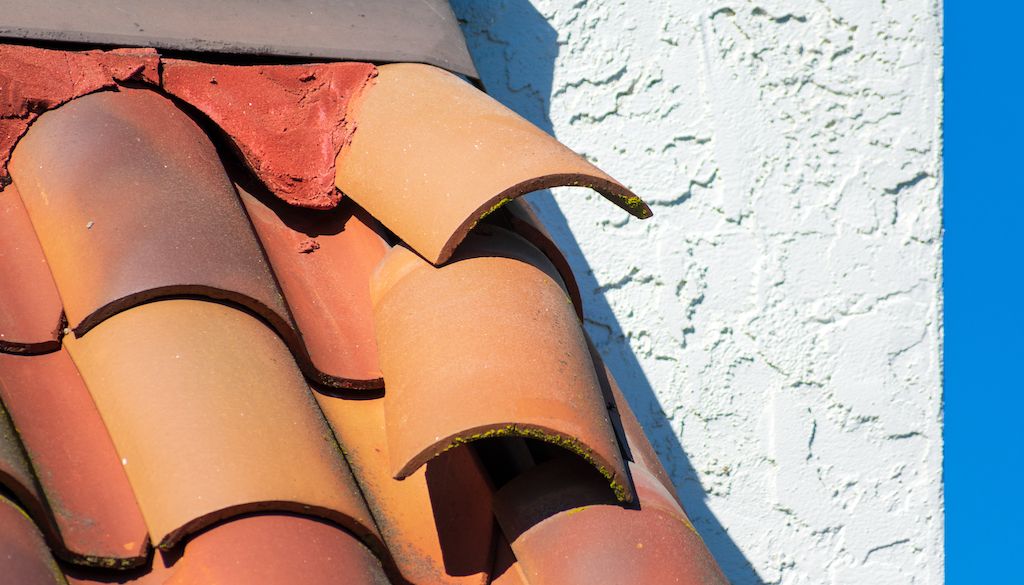
If your roof has suffered severe damage, you'll likely need a replacement. In some cases, your homeowners insurance might foot the bill. However, you need to do a bit of legwork to actually get the insurance company to pay.
Learn how to negotiate your roof replacement with your insurance company and submit a claim so you aren't stuck with thousands in repair bills.
Understand exactly what your homeowners insurance policy covers
First things first: it’s important to understand exactly what kind of insurance coverage you have for your roof.
Most standard homeowners insurance policies have specific rules for when they’ll cover roof damage. Homeowners insurance generally covers only damage caused by certain perils. Policies vary, but the most common perils that homeowners insurance may cover are:
- Falling object, like a tree or telephone pole
- Fire
- Hail or sleet
- Ice
- Lightning strike
- Snowstorm
- Windstorm
If your roof is failing because of general wear and tear or old age, your insurance company is unlikely to help.
Before submitting your roof insurance claim, make sure the damage is covered under the terms of your plan. If it isn’t covered, you’ll likely have a hard time negotiating a roof replacement.
Find out if there’s a limit on the roof’s age
Your homeowners insurance policy may also provide limited coverage depending on your roof’s age. For example, if your roof is over 20 years old, your homeowners insurance may not pay to replace it — even if it suffers covered damage.
Instead, your insurance company may offer you a payment for the roof’s actual cash value, which would likely be less than the current replacement cost.
Gather proof that you’ve maintained your roof
Insurance companies often need proof that you’ve maintained your roof over the years. Even if your roof was damaged by a covered peril, the company will look for hazards and negligence that contributed to the damage.
Hazards are basically risk factors that increase the likelihood of a peril. In the case of a roof, a hazard might be loose shingles you neglected to replace, which led to more of the roof blowing away in a storm. Or it could be that the pile of leaves you neglected to clean from your gutters ignited in the summer heat and started a fire. If the insurance company finds too many hazards, it may deny your claim.
Do everything you can to prove you maintained your roof. When submitting your claim and negotiating with your insurance company, collect and submit any receipts for repairs you’ve done over the years. Also gather pictures of your roof before and after it was damaged.
Inspect the roof to see what’s damaged
Take a closer look to see how badly your roof was damaged before you contact your insurance company. This is an important step for gathering evidence. Bring your camera along and take as many photos as you can to highlight the damage. You may also want to bring binoculars to help you see better.
Follow these steps:
- Start at ground level and walk around your home to see the roof from all angles.
- Take note of any damage to the gutters and downspouts.
- Look at the ground to see if any pieces of your roof have fallen.
- Take notes to document and describe everything you see.
Once you’ve surveyed everything you can from the ground, it’s time to get higher. If it’s safe, use a ladder to climb onto your roof to better assess the damage up close. Make sure you have a partner with you to help hold the ladder. Also be sure to wear the proper safety equipment, including eye protection, gloves and non-slip shoes.
However, don’t get on top of your roof if you’re unable or uncomfortable. Instead, consider hiring a professional roof inspector to complete this task.
Call roofing contractors for an estimate
A professional roofing contractor can provide a ballpark estimate for the repair or replacement cost. It’s good for you to know the cost in case your insurance company doesn’t offer you a fair settlement and tries to low-ball you. Your insurance company may also ask for estimates when you file your claim.
The other benefit of calling in a roofing contractor to inspect your roof is that they can make temporary repairs to prevent even more damage. For example, if your roof has a giant hole in it that’s letting water leak into your home, the contractor may be able to do a quick patch to stop additional water damage. Remember to save your receipt after the contractor makes the quick repair.
File a claim ASAP
Once you’ve gathered all of your evidence, it’s time to file the claim with your homeowners insurance. Find out whether your insurance allows you to do this online or whether you should call your agent.
Present all of your evidence in a clear, easy-to-read format. If you have notes from a contractor, make sure they’re legible.
Make sure you act quickly, as insurance companies may deny your claim. If you wait too long to file a claim and don’t make repairs, any additional damage that occurs in the meantime might not be covered.
After you’ve sent in your claim, the insurance company will likely send out an insurance adjuster to conduct their own inspection of your roof. Make sure you have a packet of all your evidence printed and ready to give to them just in case they don’t have their papers with them.
If your insurance agrees to pay a smaller-than-expected amount after you submit your claim, you can try to negotiate by getting more estimates and advice from local contractors. There’s no guarantee your insurance will change its decision — but it doesn’t hurt to try.
Mistakes to avoid when filing a claim
When you’re filing your insurance claim for roof damage, there are a few things you’ll want to avoid throughout the process:
- Taking too long to file your claim: The longer you wait to file your claim, the longer the process will take. File your claim ASAP.
- Waiting for your insurance to approve any emergency repairs: If your roof is allowing water to pour into your living room, you need to patch it right away to prevent further damage. As long as your claim ends up being approved, your insurance should pay for this initial bill as well as the final repairs.
- Not understanding the specifics of your policy: Thoroughly read your policy so you know what is and isn’t covered. For example, there may be a stipulation on how much your insurance will reimburse you if your roof is over a certain age.
- Skipping out on documentation: Get everything in writing, and record everything that happens in the process. This will help you if your insurance tries to backtrack or misplaces important records it needs to process your claim.
- Not having all the details: Make sure you know when your roof was installed and what damaged it. Compile all of these facts before submitting your claim. Being too general can lead to a denial or delays.
- Not following up after submitting your claim: Follow up with your insurance company regularly to keep things on track and avoid delays. After all, the faster it approves your claim, the faster you can get your roof repaired or replaced.
- Choosing an unlicensed contractor: Insurance companies want to know they’re paying for quality work, so they’ll only cover future damage if you choose a licensed contractor. And when you’re going through the claim process and receiving an offer, they will likely require you to use a licensed contractor to restore your roof to its pre-loss condition. Ask the contractor for proof of insurance and a contractor’s license before they start working on your roof, and see whether you need to submit that information when filing your claim.
Hire a roofing contractor near you
Choosing a reputable roofing company near you is the best way to make sure the job is done right. Download the Thumbtack app now to browse nearby professionals and hire your perfect match.
How it works.
Search.
Browse profiles, see prices and use filters to find pros who match your project.
Chat.
Contact the pros you like to discuss project details.
Hire.
Check pro availability and book appointments right in the app.
Find local pros for your project
Tell us what you're looking for and we'll show you pros right for the job, with prices.